
Disclosure: Some links in this article may be affiliate links. If you buy a policy through them, we may earn a commission at no extra cost to you.
“How much will health insurance cost me?” is the first budget question every American asks before moving to South America, and the answers online range from “$70 a month” to “$1,000 a month”. Both can be true. The price depends on four things: the country, your age, whether you choose a local or international plan, and whether the plan covers you in the US.
This guide brings together the latest published prices for the five most popular countries and for international plans, broken down by age, so you can build a realistic budget.
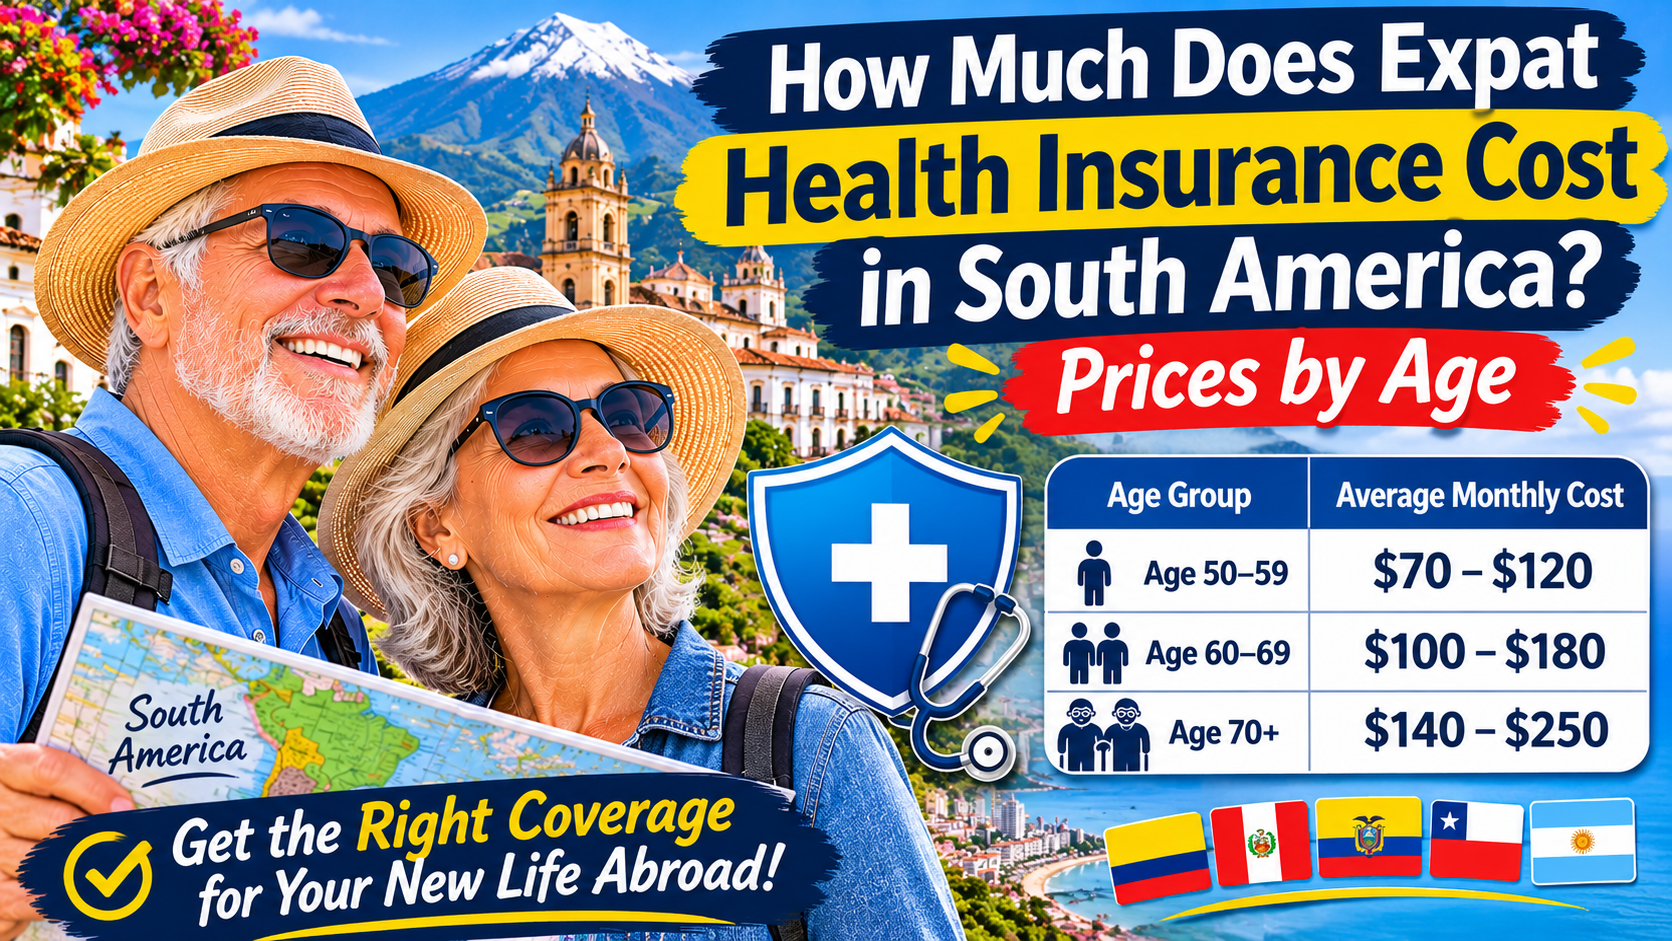
The short answer: A healthy 60- to 65-year-old can get local private coverage for roughly $70 to $250 a month in most of South America. Public systems open to legal residents can cost even less, from about $58 to $85 a month in Colombia and Ecuador. International plans that exclude the US typically run about $155 to $240 a month at 65 for a mid-tier plan with a high deductible, rising sharply at 70 and 75. Adding US coverage roughly doubles the price.
| Country | Local private (age ~60–65) | Public option for legal residents | Note |
|---|---|---|---|
| Ecuador | ~$70–$230/month | IESS: 17.6% of declared income, from $84.83/month (2026) | Some local plans close to new members at 70–75 |
| Colombia | Prepagada ~$150–$250+/month over 60 | EPS: 12.5% of 40% of income, from ~$58/month (2026) | Most prepagadas cap entry around 60 |
| Uruguay | Mutualista ~$70–$150/month | Public ASSE network | Premium private plans ~$325–$400+ |
| Chile | Isapre | Fonasa: 7% of taxable income | Isapres use health declarations |
| Argentina | Prepaga ~$150–$250/month | Public hospitals | Prepagas can’t reject applicants over 65 |
Approximate 2026 figures from the sources cited in each country section below. Public contributions tied to the minimum wage change every January.
Prices Country by Country
Ecuador: the lowest prices for full-time residents
A basic SaludSA policy for a 60-year-old can cost as little as $70 to $72 a month, typically covering 80% of doctor visits, 100% of hospitalization and 60% of medications (CuencaHighLife). At 65, private plans range from about $70 to $230 or more a month, with deductibles from about $180 to $5,000 (CuencaHighLife guide). Premiums rise at age bands; one expat saw a 20% increase at 60 (Expat.com forum).
The public IESS system costs 17.6% of declared income, with a 2026 minimum of $84.83 a month (El Comercio). For comparison, International Living cites a US premium of about $1,200 a month for a 60-year-old man versus about $70 in Ecuador (International Living).
Colombia: cheap public care, pricier private care after 60
Self-employed residents pay 12.5% of a contribution base equal to 40% of their income, never less than one minimum wage (Colombia Move). At the 2026 minimum wage, that floor is about COP 218,900, roughly $58 a month.
For private medicina prepagada, a realistic 2026 range is $80 to $120 a month under 40, $120 to $180 between 40 and 60, and $150 to $250 or more over 60 (Colombia Move). One expat reported paying COP 600,000 to 800,000 a month at 63, with a jump of 25% to 30% at 65 (Expat.com forum). Keep in mind that Pensionado visa holders generally can’t join the EPS and must budget for private or international coverage instead. (See Article 4.)
Uruguay: hospital memberships at a fixed fee
Most expats join a mutualista, a private hospital cooperative, typically for about $70 to $150 a month (Global Citizen Solutions). Premium private plans cost around $325 to $400 or more a month and often have age limits (Out of Your Comfort Zone).
Chile: income-based public system, underwritten private plans
Workers, pensioners and other contributors generally pay 7% of taxable income toward health coverage and choose whether it goes to the public Fonasa or a private Isapre. Isapre plans cost about CLP 80,000 to 300,000 or more a month in total, depending on age, tier and dependents (expat.cl). That is roughly $85 to $320.
Argentina: regulated price bands
Most retirees buy a private prepaga; a budget plan from providers such as Sancor Salud or OSDE typically costs $150 to $250 a month (Expats Argentina). By law, the price of the oldest age band can’t be more than three times the price of the youngest (Government of Argentina). Because of inflation and currency swings, dollar prices can change quickly.
Peru and Brazil
Most American expats in Peru buy private health insurance and use well-known private clinics (Wise), but we didn’t find reliable published price ranges for either country. Get at least three quotes for your age.
International and Travel Insurance: Prices by Age
International health insurance
International plans are priced by age band, and the jumps are steep. One 2026 cost guide estimates that a mid-tier plan covering worldwide excluding the US, with a $2,500 annual deductible, runs roughly $155 to $240 a month at 65 and $240 to $360 by 70. Premiums typically jump at 65, 70 and 75, with the largest increase usually at 70 (Expat Retire Guide).
Richer plans with low deductibles cost much more. Across the market, international coverage ranges from roughly $1,500 a year for a young person on a basic plan to $15,000 or more a year for comprehensive coverage for older adults (Free Market Healthcare).
The US effect: one insurer’s published averages show about €186 a month for worldwide coverage excluding North America versus about €388 a month when the US and Canada are included (Expatriate Healthcare). That is roughly double, which is why most retirees in South America exclude the US and rely on Medicare Part B for trips home.
| Age | Mid-tier international plan, excluding the US, $2,500 deductible | What to expect |
|---|---|---|
| 60–64 | Lower than at 65; get quotes | Best time to apply: more insurers, fewer exclusions |
| 65 | ~$155–$240/month | Medicare decisions happen at the same time |
| 70 | ~$240–$360/month | Usually the biggest single jump |
| 75+ | Higher again | Fewer insurers accept new members |
Ranges from the 2026 cost guide cited above. Low-deductible or premium plans can cost two to three times more.
Nomad plans
SafetyWing Nomad Insurance Essential starts at about $62.72 per four weeks for ages 18 to 39, with steps up at 40, 50 and 60 (We Seek Travel). Nomad Insurance Complete starts at about $177.50 a month for ages 18 to 39 (ExpatDen).
Travel medical insurance for trips
Squaremouth’s purchase data from June 2025 to June 2026 shows the average travel medical policy costing $94 for travelers aged 60 to 69 and $144 for those 70 and older. Travelers over 70 pay at least 53% more on average than any other age group (Squaremouth).
What Drives the Price
- Age band. The single biggest factor. Prices step up at fixed ages, commonly 60, 65, 70 and 75.
- Coverage area. Including the US can roughly double an international premium.
- Deductible. Moving from a $0 to a $2,500 or $5,000 deductible can cut the premium substantially. It works best if you have savings to cover the deductible.
- Outpatient and prescriptions. Hospital-only plans are far cheaper; adding outpatient care, medications, dental and vision raises the price.
- Health history. Underwritten plans may exclude conditions or add a surcharge. Public systems such as IESS don’t underwrite.
- Currency. Plans priced in pesos (Colombia, Chile, Argentina) can change in dollar terms as exchange rates move. Ecuador’s economy uses the US dollar.
Total Yearly Cost: Three Real-World Profiles
Premiums are only part of the bill. These examples include an allowance for deductibles, co-pays and uncovered costs.
| Profile | Coverage setup | Premiums per year | Out-of-pocket allowance | Approx. total per year |
|---|---|---|---|---|
| Couple, 63 and 61, living in Cuenca, Ecuador | Two local private plans (~$90–$150 each per month) | ~$2,160–$3,600 | ~$500–$1,500 | ~$2,700–$5,100 |
| Single retiree, 67, Pensionado visa in Medellín | International plan excluding the US (~$200–$300/month) + Medicare Part B ($209.40/month in 2027) | ~$4,900–$6,100 | ~$500–$2,500 (deductible) | ~$5,400–$8,600 |
| Resident, 55, in Medellín with a cédula | EPS ( | ~$2,100–$4,000 | ~$200–$600 | ~$2,300–$4,600 |
Illustrative estimates built from the price ranges cited in this article. The international premium for a 67-year-old is interpolated between the published ranges at 65 and 70. Keeping Medicare Part B is optional; see Article 11.
What this tells you: for most retirees, total health costs in South America land between about $2,500 and $9,000 a year, often less than a single year of US premiums before Medicare. The biggest swing factor isn’t the country; it’s whether you need an international plan or can use local and public options.
How to Pay Less Without Being Underinsured
- Exclude the US from international plans. It is the single biggest saving. Use Medicare Part B or a travel medical policy for trips home.
- Raise your deductible, but only to an amount you could pay tomorrow. A $2,500 deductible makes sense if you keep at least that much in an emergency fund.
- Combine public and private coverage. In Ecuador, many expats join IESS once they have their cedula and keep a low-premium, high-deductible private plan for fast access to private hospitals (CuencaHighLife guide). In Colombia, residents who can join the EPS often add prepagada.
- Buy before the next age band. Applying a few months before turning 65 or 70 can lock in a lower price and broader acceptance.
- Pay annually if the insurer offers a discount. Some insurers discount annual payment; one example is a 6% reduction compared with monthly installments (Expatriate Healthcare).
- Cover catastrophes first. If budget is tight, prioritize hospitalization, cancer care and evacuation over routine extras. You can pay for small doctor visits out of pocket at local prices.
- Compare like for like. Get at least three quotes with the same deductible, coverage area and benefits, or the cheapest quote may simply be the thinnest plan.
[Affiliate button: “Get free quotes from international insurers”]
Where Not to Cut Corners
- Evacuation coverage if you live or travel far from major cities.
- Annual and lifetime limits: a $50,000 limit can disappear in one hospital stay.
- Renewal terms: a cheap plan that can drop you at 75 may cost you far more later.
- Visa compliance: a plan that doesn’t meet your country’s visa wording can cost you your residency. (See Articles 1 and 4.)
Frequently Asked Questions
What is the average cost of expat health insurance in South America?
For a healthy person around 60 to 65, local private plans typically cost about $70 to $250 a month, depending on the country. International plans excluding the US run about $155 to $240 a month at 65 for a mid-tier plan with a high deductible, and more for richer coverage.
Which South American country has the cheapest health insurance for expats?
Ecuador is among the cheapest: basic local plans start around $70 a month at 60, and the public IESS system starts at $84.83 a month (2026 rate) once you are a resident. In Colombia, the public EPS minimum is about $58 a month for residents who can enroll.
How much does health insurance cost at 70 in South America?
International plans typically see their biggest price jump at 70, to roughly $240 to $360 a month for a mid-tier plan excluding the US with a high deductible. Local plans may be cheaper, but some stop accepting new members at 70 or 75.
Is it cheaper to include or exclude the US?
Excluding the US is much cheaper. One insurer’s published averages show premiums roughly doubling when the US and Canada are included.
Do I still need to pay for Medicare?
It is optional, but dropping Part B can trigger lifetime penalties if you return. In 2027, Part B costs $209.40 a month. (See Article 11.)
How much should I budget for health care in total?
Include premiums plus deductibles, co-pays and uncovered costs. In our examples, total yearly costs range from about $2,300 to $8,600 depending on age, country and the type of coverage.
The Bottom Line
Health insurance in South America is affordable compared with the US, but the range is wide. Local private plans for people in their early 60s often cost $70 to $250 a month, public systems for residents can cost less, and international plans excluding the US typically start around $155 to $240 a month at 65 and climb at 70 and 75. Build your budget on total yearly cost, not just premiums, buy before the next age band and never trade away evacuation coverage or high limits to save a few dollars.
Keep reading:
- Best International Health Insurance for Expats in South America (Article 29)
- Retiring in South America at 65+: How Age Changes Your Insurance Options (Article 27)
- Local vs. International Health Insurance in South America (Article 37)
- Best Countries in South America to Retire for Affordable Healthcare (Article 19)
This article is for general information only and is not insurance or financial advice. Prices are approximate, change frequently and depend on your age, health and plan; get personalized quotes before you buy.
Sources
- Top private health insurance plans for expats — CuencaHighLife
- IESS vs. private plans — CuencaHighLife
- Premium increase at 60 — Expat.com forum (Ecuador)
- IESS minimum contribution 2026 — El Comercio
- US vs. Ecuador premium — International Living
- EPS enrollment and contributions — Colombia Move
- EPS vs. prepagada costs 2026 — Colombia Move
- Prepagada prices at 63–65 — Expat.com forum (Colombia)
- Living in Uruguay 2026 — Global Citizen Solutions
- Health insurance in Uruguay — Out of Your Comfort Zone
- Health insurance for expats in Chile 2026 — expat.cl
- Argentina Pensionado visa and prepagas — Expats Argentina
- Prepagas and age — Government of Argentina
- Moving to Peru from the USA — Wise
- Expat health insurance cost guide 2026 — Expat Retire Guide
- International health insurance cost 2026 — Free Market Healthcare
- How much is international health insurance? — Expatriate Healthcare
- SafetyWing pricing — We Seek Travel
- SafetyWing review — ExpatDen
- Travel medical insurance cost by age — Squaremouth
Deja una respuesta